Only a Brief Window Left Before Dystopian Systems of Identity, Money, and Surveillance Become Irreversible. Outstanding Analysis by Eric Daniel Buesing
By Michel Chossudovsky and Eric Daniel Buesing, Michel Chossudovsky
What if the most consequential transformation in human history was designed to be invisible until it was too late to stop?
Blockchain, programmable money, and digital identity are converging into something historians will either call the greatest innovation of the century or its most sophisticated trap.
The infrastructure is already in place. The only question that remains is what unfolds once the system is fully locked into place. That is why it is so important for readers to share this free essay, so their loved ones can prepare for the inevitable future now taking shape.
Somewhere between the Bitcoin price charts and the Senate procedural votes and the endless argument about which crypto is a security and which is a commodity, something genuinely historic is being assembled. Not debated. Not proposed. Assembled. Quietly, deliberately, and almost entirely out of public view.
Most people, when they hear the word “crypto,” think speculation, meme coins and volatility. Tech bros getting rich or getting wrecked. That’s not an accident. That’s the background noise, engineered to be loud enough that you never hear what’s behind it.
What’s underneath it is the architecture of a financial system that will know everything you buy, everything you earn and everywhere your money goes.
It will have the technical capacity to decide, in real time, whether your money is permitted to work at all. Not based on whether you’re breaking the law. Based on whether you’re in compliance. With whatever compliance means when the system goes live. Those are very different things, and the distance between them is the distance between a free society and something that makes 1984 look like a rough draft. Orwell’s telescreens watched you. This watches your wallet. And unlike a telescreen, it doesn’t just observe. It decides.
The CLARITY Act, stalled in the Senate but still alive after a 49 to 50 vote in September, is the surface layer; the regulatory paperwork being filed on a building that is already largely constructed.1 By the time most people understand what’s been built, the construction will be finished.
This Pattern Is 5,000 Years Old
The people building it are not inventing anything new. They are running the oldest playbook in human history, just on faster hardware. In my book The Hidden Hand: Wealth, Power, and Control from Pharaohs to Corporations,
I spent 22 years documenting a pattern that repeats across every civilization, every era, every technological shift.2
The names change and the tools change but the underlying architecture does not.
Elites across five millennia have used four interlocking mechanisms to maintain control over populations vastly larger than themselves.
Coercion: make economic survival contingent on compliance.
Alignment: capture the institutions that shape what people believe is possible.
Amnesia: ensure each generation forgets that alternatives ever existed.
Conflict: keep the population fighting itself so it never unifies against the people who manufactured the crisis in the first place.3
***
The Egyptian grain store controlled your food.
The medieval guild controlled our labor.
The industrial minimum wage controlled humanity’s survival.
Each era found the chokepoint, the things people cannot live without, and made access to it conditional on compliance with whoever controlled it.4
Control it at the transaction level, with the technical capacity to permit or deny any individual exchange in real time, and you have achieved what no pharaoh, emperor, or colonial power ever managed: total economic coercion without a single soldier.
Not by threatening people, but by programming the money itself to refuse.
That is what is being built.
And the blueprint has been sitting in plain sight for decades, written in clear language in documents almost no one reads.
They Told Us
Carroll Quigley was a Georgetown historian who was granted unprecedented access to the papers and secret records of the network behind the Council on Foreign Relations. He spent two years in them. Then he wrote Tragedy and Hope describing what he found without apology:
“The powers of financial capitalism had another far-reaching aim, nothing less than to create a world system of financial control in private hands able to dominate the political system of each country and the economy of the world as a whole.”5
He wasn’t warning us. He actually thought it was a good idea. Basically inevitable and that its architects were well-intentioned. That is perhaps the most disturbing part of his book. When the people designing the cage believe they are building a park, the cage gets built with genuine enthusiasm.
Eight years earlier, René Wormser published what he found as general counsel to the 1954 congressional Reece Committee investigation into America’s most powerful tax-exempt foundations.6 Primarily the Carnegie, Rockefeller, and Ford foundations. The committee’s researchers found a coordinated network that had quietly divided American society into territories of influence:
Carnegie controlling international education, Rockefeller controlling domestic education, Ford deploying the financial muscle.7 No one had announced this. No public vote was taken. The foundations simply funded the institutions that shaped what the next generation would believe, until the beliefs they wanted were the only ones available. I write about this social conditioning which has occurred across this entire epoch of humanity in my forthcoming book called The Illusion Architects: How Elites Shape Culture Consciousness and Reality. (TrineDay, January 2027)
When the Reece Committee published its findings, the foundations mobilized and the media attacked. The hearings were shut down within weeks. The report was released just as McCarthy was being censured, so anything resembling anti-establishment investigation was instantly discredited.8The playbook worked perfectly.
Wormser’s investigation exposed one layer of concentrated power: the philanthropic foundations and their quiet division of influence over American institutions. A separate layer, quantified decades later by a 2011 ETH Zurich study, operates through equity itself. Researchers Vitali, Glattfelder, and Battiston mapped the ownership network of 43,060 transnational corporations and found that control ultimately flowed to a core “super-entity” of just 147 firms, most of them financial institutions, that collectively controlled 40 percent of the total wealth in the global corporate network through cascading shareholding relationships.9 The study drew on 2007 data. Barclays topped the list. JPMorgan Chase, Goldman Sachs, State Street, and Vanguard all appear in the upper ranks. BlackRock was there too, nearly half owned by Merrill Lynch and managing just over $1 trillion at the time. Two years after the study’s data were collected, BlackRock acquired Barclays Global Investors for $13.5 billion, vaulting to $2.7 trillion overnight and positioning itself to become the largest asset manager on earth. It now manages over $15 trillion.10
The concentration the study measured in 2007 has only deepened since, and the same institutions now sit at the center of the digital financial infrastructure being assembled today. And then there is Vanguard, which manages roughly $12.8 trillion and ranks as the second largest asset manager on earth, yet has no identifiable outside owner. It is structured so that the funds own the company and the company runs the funds, a recursive loop that makes it effectively unownable and unaccountable in any conventional sense.11
Nobody can tell you who controls it, because the answer the structure gives you is everyone and no one simultaneously. That is not a conspiracy theory. It is the answer you get when you look it up. What Wormser saw operating through foundations and culture, this study found operating through capital itself. Two mechanisms, one architecture, and the people running both are building the system that will decide whether your money works tomorrow. I’ve written that history is not a series of disconnected events. It is a single long project with a very small number of actors.
The Upgrade
The current financial system, built around SWIFT and its postwar institutional descendants is slow, inefficient, and opaque in ways that limit what can be done with it as a control instrument. It often takes days or weeks to settle transactions. It requires human intermediaries at every step. It cannot be updated in real time and it cannot be programmed. What is being built to replace it can.
The new infrastructure, assembled through more than a thousand partnership agreements whose terms the public has never seen, runs on blockchain rails with programmable money at its core.
Money that can expire.
Money that can be restricted to certain categories of purchase.
Money that can be limited to certain geographic zones.
Money that is linked to your verified digital identity and social credit score so every transaction you make is permanently associated with you, in real time, in a ledger that cannot be altered.
The pieces are already operational. As of May 2026, 146 countries were exploring a government-controlled digital currency. Seventy-seven had moved past that. Not studying the idea. Not holding meetings about it. They were already in development, testing, or launch, and 41 pilots were running in the real world with real money.12
China’s e-CNY is the largest of them, having processed more than 3.4 billion transactions worth roughly $2.3 trillion, and the same central bank that issues it also runs the zhengxin credit system, which holds financial records on 1.14 billion Chinese citizens. Issuance and scoring sit under one roof.13India forced its people into digital payments by invalidating 86 percent of its physical currency overnight in 2016, then ordered every bank account linked to its biometric identity system in 2017, leaving a population of over a billion people with no choice but to enter the digital ledger.14
Given the growing accusations of AI agents quietly infiltrating banking systems, what happened in India may not be as far off for the rest of the world as most people assume. Nigeria launched Africa’s first retail central bank digital currency in October 2021, and when the population largely refused it, with 98.5 percent of eNaira wallets sitting unused in any given week a year after launch, the central bank kept it running anyway.15 These are not future scenarios. They are current deployments, documented in the records of the institutions that built them. The infrastructure gets built whether anyone asks for it or not. Demand was never the point.
In the West, the infrastructure is being laid more gradually, through financial technology partnerships, regulatory frameworks, and the normalization of digital identity requirements in payment systems.
The crisis that will justify flipping the switch from optional to mandatory has not arrived yet. But when it does, the system will be ready. It is already operational and already trusted by the largest financial institutions. And once a population has integrated the payment systems into every pharmacy, every grocery store, and every employer’s payroll, removing it becomes functionally impossible.
Silence as Strategy
Foundations like the Rockefeller Foundation, the Gates Foundation, and the Open Society Foundations have collectively channeled hundreds of millions of dollars into the digital identity and payments infrastructure being built right now.
The Gates Foundation alone committed $200 million to what it calls digital public infrastructure, a category that explicitly includes digital ID systems and civil registry databases, and it partners with the World Bank’s Identification for Development initiative on national ID rollouts.
Rockefeller and Open Society served as research collaboration partners on the McKinsey study that made the economic case for universal digital ID.
Digital identity systems are always presented as tools for financial inclusion.16 The language is always the language of progress and charity. The result is always the same monitoring and control layer underneath.
This is not new behavior. The Rockefeller Foundation funded Alfred Kinsey’s research beginning in 1941, with grants that by 1947 reached $40,000 annually, to reshape American sexual norms, a methodology later attacked in Congress and criticized by statisticians for its unrepresentative sampling.17
The Carnegie Corporation funded the American Historical Association’s Commission on the Social Studies, whose 1934 report concluded that the age of individualism and laissez faire in economy and government was closing.18
The Ford Foundation built the behavioral sciences infrastructure that became the foundation for modern social engineering.19 All of this was presented as enlightened philanthropy. Wormser’s 1958 warning has not aged one day saying:
“When they do harm, it can be immense harm, there is virtually no counter-force to oppose them.”20
The secrecy surrounding the new financial infrastructure follows the same logic. You build it first. You embed it in enough institutions that it becomes impossible to uproot. You let the public-facing story, decentralization, faster payments, financial inclusion for the unbanked, do the work of normalization.
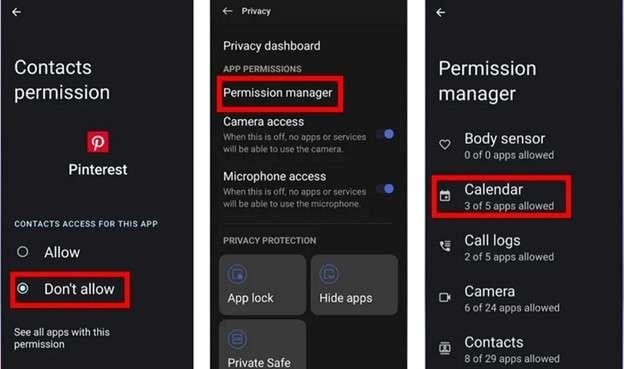
Then, when the conditions are applied, the population has been living inside the infrastructure long enough that they cannot imagine existing without it. As a prime example of how this works, examine the permissions on your phone. They began as opt-in choices. Then they were switched to automatic defaults. Today many of them are compulsory. Deny them and the phone, or the services you rely on, simply stop functioning.
Ripple alone is reported to hold more than 1,700 banking agreements, and the terms of almost none of them are public.21 While the public watched the Bitcoin spectacle, the real infrastructure deployed beneath it.
AI Is the Warden
No human administrator can monitor every transaction across billions of accounts, evaluate each one against a set of programmed conditions, and permit or deny the exchange in real time. A sufficiently advanced AI system can, and will.
The AI systems that already shape what populations can find when they search for alternatives are being integrated into the financial ledger, converging with money control into the same architecture, accountable to the same network of interconnected firms that Carroll Quigley documented in 1966 and the ETH Zurich researchers quantified in 2011. This is not the paranoid fantasy version of AI risk. It is the operational description of systems that are being built right now by companies whose names appear on the Davos attendee list every January. The risk isn’t that the AI goes rogue. The risk is that it works exactly as designed, and the design is a coercion engine with no off switch and no appeals process.22
Orwell imagined the Party needed armies of human watchers to maintain control. The modern version needs none. The compliance check is automated, instantaneous, and applied at the point of transaction. You are not detained or arrested. Your money simply does not work until your status changes.
The Consent Architecture
What makes this system so effective is that it needs your participation to function, and it makes participation the path of least resistance. It is faster than what it replaces. It’s cheaper and genuinely more convenient. The fraud protections are real.
The cross-border capabilities are real. The financial inclusion for people who currently have no banking access is real. None of those benefits are lies. They are the SOMA! The delusion that makes the cage worth entering.
We have been socially conditioned to accept our fate, as I have previously written, by authors such as Ayn Rand, Aldous Huxley, George Orwell, and an army of other writers and filmmakers.
Propped up by the system that sought to prepare humanity for a controlled future, these figures paved the way and primed human minds to accept our dystopia. As Oscar Wilde observed, life imitates art.23 Huxley understood something Orwell did not fully account for: the most durable form of control is not the kind imposed on people, but the kind they choose because the alternative looks worse.
In Brave New World, no one is forced into their social role. They are conditioned to love it, and the conditioning begins before they are old enough to question it.24
The financial system being built works the same way. The conditioning happens through adoption. Once you have structured your financial life around a payment system, once your employer uses it, your pharmacy uses it, your landlord uses it, the cost of opting out becomes functionally prohibitive. Not illegal. Just impossible as a practical matter. And at that point, the programmable conditions can be tightened incrementally, each adjustment too small to trigger mass resistance, each one building on the last until the space for autonomous economic action has closed entirely.
This is how every elite coercion system in history has worked. Make yourself indispensable first, then introduce the conditions. By the time the conditions arrive, exit is no longer possible. We are in the indispensable phase right now. The doors are open. The terms are reasonable. The conditions haven’t been called yet.
What the Silence Actually Means
The technology works. That much is settled. The questions that matter are who controls it, toward what ends, with what accountability, and whether those answers will be decided democratically or simply appear as a feature in the next update.
The people who build infrastructure of control have always believed, with genuine conviction, that they are building it for everyone’s benefit. Quigley said so. The Carnegie Endowment’s trustees wrote as much in the minutes that shook Catherine Casey badly enough that she could never practice law again.25 Every previous version of this system came with the same rationale: stability, efficiency, order. And every time, that was true. That was never the problem. The problem was always that they were also providing themselves with a mechanism of control that no future crisis, no election, no popular movement could dislodge, because the mechanism was embedded in the infrastructure of daily life. That is what is being built now, at a scope and precision that makes every previous version look primitive.
The cage is being built with your consent. One frictionless transaction at a time. And the door will not lock from the outside. You will close it yourself, because it is faster and cheaper and more convenient than leaving it open. The only question is whether you understand what you are stepping into before the door closes behind you.
Is There a Way Out of the District?
Elites want to build 15-minute cities designed to function like self-contained districts under centralized control. Every control system ever built needs participants. It needs them before they understand what participating means. The window between now and the moment programmable conditions get written into the code and the alternatives disappear is the only leverage ordinary people have, and it is closing.
The new financial system runs on a global messaging standard called ISO 20022, which became mandatory for all bank-to-bank cross-border payment instructions on the SWIFT network in November 2025.26
Every major bank on earth now speaks this language. A small set of cryptocurrencies is designed to work with it: XRP (Ripple), XLM (Stellar), HBAR (Hedera), ALGO (Algorand), IOTA, QNT (Quant), XDC (XDC Network), and ADA (Cardano).27 These are not speculative lottery tickets. They are the assets denominated in whatever the architects of the new system have decided money will be, the bridge layer between the old rails and the new ones. The institutions accumulating them know exactly what they are. The retail public, distracted by Bitcoin’s price action and Washington’s procedural votes, largely does not.
Think about what it would have meant to see the internet clearly in 1994. Not the dot-com mania that came later, not the sock puppet commercials and the vaporware valuations, but the actual structural reality underneath all of it: that TCP/IP was going to become the nervous system of global commerce and that every business, every transaction, every relationship would eventually run through it. Most people could not see it. The noise was too loud, the timeline too uncertain, the technology too abstract. The people who did see it, not the speculators chasing the bubble but those who understood what the protocol actually did, had a window of clarity that closed fast and never reopened. That same window exists right now with ISO 20022. Not the hype. The protocol. And this time the institutions on the other side of the trade have been accumulating quietly for over a decade while the public watched Bitcoin.
As previously noted, popular works such as The Hunger Games have been elevated to mass success in part because they culturally condition audiences to accept a world of total economic control. In the film, the Capitol controlled everything that moved through Panem: every calorie, every resource, every transaction. The districts possessed no economic autonomy because they held no assets the Capitol had not already claimed.
The people who will survive this transition from the current system to the next with any meaningful freedom will be those who hold something of value in the new system’s own language, before the Capitol finishes building the walls.28
This is not financial advice. It is history.
Every major monetary transition has rewarded the people who recognized it early and punished those who held onto the instruments of the old system past the point of no return.
The Medici Bank dominated European finance for nearly a century because its founders moved to the new bill-of-exchange economy while their competitors were still thinking in the old terms.29
The Fugger family of Augsburg achieved similar dominance in the early sixteenth century by recognizing that control of silver mining and papal finance, the chokepoints of the emerging Habsburg monetary order, was worth more than any individual transaction.30 The Bretton Woods architects understood the same thing in 1944.31 The institutions behind those 1,700 plus banking agreements understand it now.
There is still time to understand it too. Not infinite time, but time. The gate has not latched shut yet. The system is live but not mandatory. The alternatives still exist. The ISO 20022-compatible tokens are still priced as though the public does not know what they are for, because largely it does not.
That is the opening. It will not stay open forever, but it is open right now. A cage you can buy your way out of is not the same thing as a cage you cannot. What remains open is the chance to understand, and understanding has always been the first step toward freedom.
For a deeper map of how we got here, running from the first civilizations through the Reece Committee, the CFR, the 147-firm ownership web, and the surveillance capitalism architecture being deployed today, the full investigation is in The Hidden Hand: Wealth, Power, and Control from Pharaohs to Corporations, available wherever books are sold. Nothing in this article constitutes financial advice. The historical documentation cited is drawn from public records, court documents, and published academic sources. Do your own research.